South African businesses have a segmentation problem. Not necessarily because they lack data, but because they often ask too much of it.
Averages are convenient. They simplify complex markets into numbers that can be used in forecasts, presentations and marketing plans. Average household income, average spending, average basket size and average customer lifetime value all have their place.
The difficulty begins when businesses mistake those averages for actual people.
South Africa is a market where two consumers can live in the same city, earn similar incomes and shop at the same retailer, yet have fundamentally different relationships with money, convenience, technology and brands. One might prioritise price above everything else. Another might pay more for a product that saves time. A third might be willing to travel to a further store for a brand they trust.
The same product, price or proposition can mean very different things to each of them.
This matters because businesses do not sell to averages. They sell to people making decisions within particular economic, social and personal circumstances. The more those circumstances are flattened into broad consumer categories, the greater the risk of building propositions that look convincing in a spreadsheet but fail to reflect how people actually live.
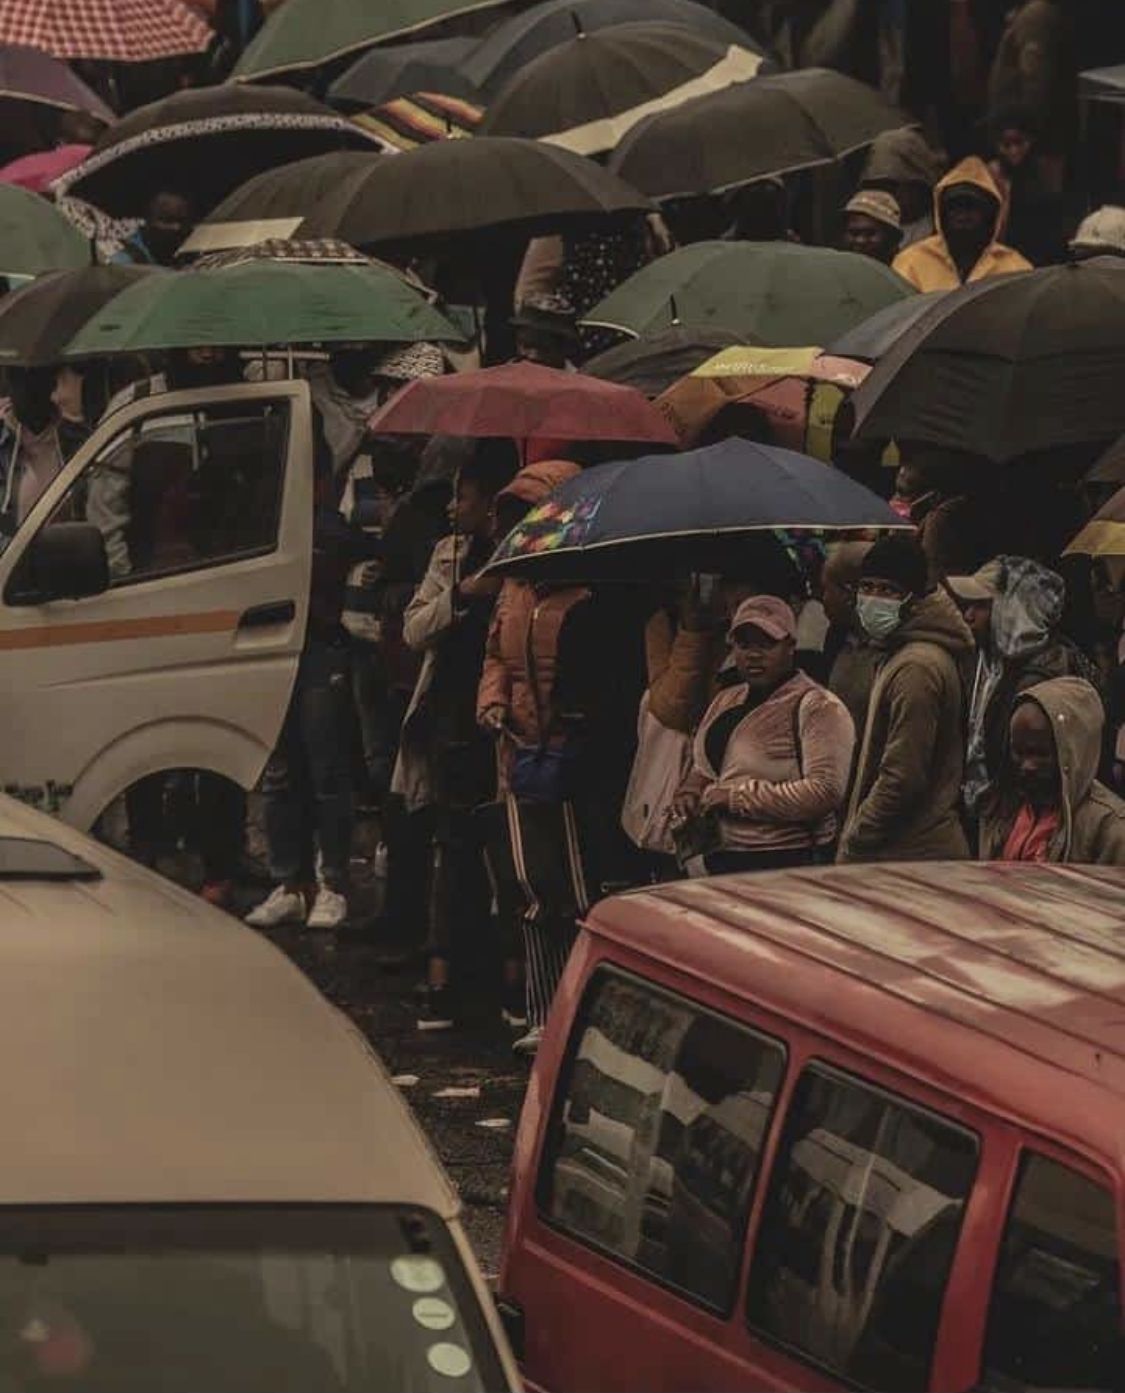
South Africa does not have a single consumer profile waiting to be discovered. It has multiple consumer realities operating within the same economy.
The average hides the market
The scale of the differences becomes clearer when we look at household expenditure.
Statistics South Africa’s 2022/23 Income and Expenditure Survey estimated average annual household consumption expenditure at R143,691. The median, however, was R82,861. That is a substantial difference, reflecting how higher-spending households pull the national average upwards.
South African household consumption expenditure, 2023
Average per year
R143,691
Median per year
R82,861
The average is approximately 73% higher than the median. These are household figures, not individual consumer spending.
The difference is more than a statistical curiosity. It affects how businesses interpret market size, estimate demand and decide which customers they are designing for.
Imagine a retailer using average household expenditure to estimate demand for a new premium product. The resulting forecast might look attractive, particularly if the retailer serves a market with a relatively high concentration of affluent households. But the national average tells the business very little about the proportion of households that can realistically afford the product, how frequently they might buy it or what they would sacrifice to do so.
The same issue appears in FMCG. A national average can conceal significant differences in purchasing frequency, pack-size preferences and the importance of promotions. A household buying in bulk once a month and one buying small quantities several times a week may contribute similar amounts to a category over time, but they face very different purchasing constraints.
Financial services face a related challenge. A consumer’s income alone does not explain their financial needs. Household responsibilities, income regularity, access to financial infrastructure and existing financial commitments can all influence which products are useful and which are simply inaccessible.
Averages are not inherently misleading. They become misleading when businesses use them to make assumptions about consumers whose circumstances differ substantially from the average.
Income explains some things. Not everything.
Income is an obvious starting point for understanding consumer behaviour. It influences purchasing power, affordability and access to products and services. But it is an incomplete explanation of how people make decisions.
Two households with identical monthly incomes can have very different amounts of disposable income. One might support a single adult. Another might support several children and contribute to the living expenses of relatives. Their capacity to spend, save, borrow or absorb an unexpected expense will differ considerably.
The composition of a household matters just as much as its income. Stats SA’s 2024 General Household Survey found that 26.9% of households consisted of a single person, while 39.4% were nuclear households comprising parents and their children. It also found that 42.4% of households were female-headed. These differences have practical implications for how households allocate resources and make purchasing decisions.
A single-person household may prioritise convenience and smaller pack sizes. A larger household may place greater value on bulk purchases and products that stretch across several people. These are potential differences worth investigating, not universal rules about either group.
The same applies to financial services. A salaried employee with predictable monthly income and a self-employed person earning an irregular income may have similar annual earnings but very different cash-flow requirements. A financial product designed around a fixed monthly repayment may suit one and create considerable difficulty for the other.
Income remains an important segmentation variable. It just simply cannot do all the work.
Businesses that rely too heavily on income bands risk overlooking the circumstances that actually shape purchasing behaviour. A more useful understanding emerges when income is considered alongside household structure, financial obligations, employment patterns and the practical realities of everyday life.
Access changes what consumers can do
South Africa’s consumer market is also shaped by differences in access. These include access to reliable transport, digital infrastructure, physical retail, financial services and even basic utilities.
Digital access is a particularly useful example because it challenges a common assumption: that widespread mobile connectivity means consumers are equally equipped to participate in digital commerce.
Stats SA’s 2024 General Household Survey found that 82.1% of households had internet access through at least one means. However, only 17.4% had access to fixed internet at home. Mobile access accounted for much of the difference. Access also varied considerably by province, with the Western Cape reporting 92% household internet access through any means, compared with 70.3% in the Northern Cape.
For an e-commerce business, this distinction matters. A customer accessing a website through a mobile phone and prepaid data does not necessarily experience digital shopping in the same way as someone with reliable fibre connectivity and a large-screen device.
Page load times, image-heavy product listings, payment processes and delivery options can all affect the shopping experience. A technically functional website may still create considerable friction for a customer with limited data or an unreliable connection.
Retailers also need to consider physical access. The availability of delivery services, collection points and nearby stores influences which purchasing options are practical. A product may be affordable and desirable, but if the customer cannot conveniently obtain it, the opportunity is limited.
Financial services face similar considerations. A digital account or lending product may be available online, but availability does not automatically mean accessibility. Data costs, identity verification, digital literacy, trust and the ability to navigate an application can all influence whether a consumer can use it.
The commercial implication is straightforward: access is not simply a distribution consideration. It shapes the products people can use, the channels through which they shop and the experiences they expect.
The problem with demographic shortcuts
Demographic segmentation remains useful. Age, income, location, gender and household structure can reveal meaningful differences between groups. The problem is treating those categories as explanations for behaviour rather than starting points for investigation.
Consider the assumption that younger consumers are naturally more comfortable with digital financial services. Age may correlate with adoption, but it does not explain whether someone trusts a particular provider, understands its fees or has a genuine need for the product.
Likewise, assuming that higher-income consumers are less price-sensitive overlooks the possibility that they are highly selective about where they spend. A consumer can afford a premium product and still choose a cheaper alternative because the additional value is not compelling.
These distinctions are particularly important when businesses combine demographic data with behavioural data. A customer who frequently purchases discounted products may be responding to financial constraints, but they may also simply enjoy finding a good deal. The transaction alone cannot establish the motivation.
This is where research needs to move beyond classification. Segmentation tells a business that consumers differ. Good research investigates why those differences exist and whether they matter to a particular commercial decision.
That requires combining quantitative evidence with qualitative understanding. Transaction data can reveal what customers buy, how frequently they buy it and how much they spend. Interviews, observation and other qualitative methods can help explain the motivations and circumstances behind those decisions.
Neither method tells the whole story. Together, they provide a more complete basis for understanding the market.
A more useful way to understand the market
For businesses operating in South Africa, the objective should not be to create an endlessly complicated segmentation model. More segments do not automatically produce better decisions. In fact, excessive segmentation can make marketing more expensive and operationally difficult without improving commercial outcomes.
The more useful approach is to identify the differences that materially affect the business.
For FMCG, that might mean understanding how household composition, shopping frequency, affordability and access influence pack-size preferences and brand choice.
For financial services, it could mean examining the relationship between income regularity, financial obligations, trust and the actual use of financial products.
For retail and e-commerce, it might involve understanding how digital access, transport, delivery costs and purchasing habits affect conversion and repeat purchases.
In each case, the starting point is a specific business question. The research should then identify which consumer differences help answer it.
There is also a need to distinguish between a market opportunity and a marketing audience. A group of consumers may have a clearly identifiable need, but that does not automatically mean it is commercially viable to serve. Businesses still need to consider market size, purchasing power, acquisition costs, distribution and the economics of meeting that need.
Good segmentation connects consumer understanding to commercial reality. It helps businesses decide not only whom to serve, but also which needs they can realistically meet.
The market is not the average
South Africa’s consumer market is often described through national statistics and broad demographic categories. Those measures are valuable. They provide a common reference point and help businesses understand the scale and distribution of economic activity.
But they are not a substitute for understanding the people behind them.
Averages can obscure differences in spending power. Demographics can conceal differences in motivation. Digital access can disguise differences in the quality of the customer experience. And a product that appears affordable at a national level may still be out of reach for the households a business hopes to serve.
None of this means that every consumer needs an individual proposition or that mass-market products have become irrelevant. It means that businesses need to be more deliberate about which consumers they are addressing and which assumptions underpin their decisions.
The South African consumer is not a single, predictable profile. Nor is the market simply a collection of income brackets waiting to be targeted.
It is a complex set of overlapping consumer realities. Understanding those realities is not an academic exercise. It is fundamental to developing products people can afford, services they can use and propositions that give them a genuine reason to choose one business over another.
The question for businesses is no longer simply how to reach the South African consumer. It is which South African consumers they actually understand.
Leave a Reply